NSC Accounting: The Six Questions That Repeat, and the Format Marks Behind Them
by Braintiq Academic Team
Accounting is unusual among NSC subjects because the format is part of the answer. In maths, a correct result written untidily is still correct. In accounting, a statement without its heading, or a figure in the wrong column, loses marks that have nothing to do with whether you understood the transaction.
That sounds unfair until you see it the other way round: format marks are the easiest marks in the subject, because they are fully predictable and require no thinking at all under pressure. You can bank them before the exam starts.
Here are the six question types that come back, and what the memo wants from each.
The foundation everything rests on
One equation, and every entry you will ever make obeys it:
$$\text{Assets} = \text{Owners Equity} + \text{Liabilities}$$
Every transaction changes at least two accounts and leaves that equation balanced. When you are lost in a question, come back to it and ask which two things moved and in which direction.
The rules for debits and credits follow from it:
- Assets increase on the debit side.
- Liabilities and owners equity increase on the credit side.
- Expenses are debited, because they reduce equity.
- Income is credited, because it increases equity.
If you can say why an expense is a debit rather than just that it is, the ledger questions stop being memorisation.
One: the Statement of Comprehensive Income
Formerly the income statement. It reports performance over a period.
The order is fixed and the order is marked:
- Sales, less cost of sales, giving gross profit.
- Plus other operating income.
- Less operating expenses, giving operating profit.
- Less interest expense, giving profit before tax.
- Less income tax, giving net profit after tax.
Those four named subtotals are each worth a mark, and each must be labelled. A column of correct numbers with no subtotals scores badly.
The adjustments are where the thinking is, and they are the same ones every year: depreciation, accrued and prepaid expenses, income received in advance, bad debts and the provision for bad debts, and trading stock deficit.
The habit that saves you: for each adjustment, write which two accounts move before you touch the statement. Most adjustment errors are one-sided entries made in a hurry.
Two: the Statement of Financial Position
Formerly the balance sheet. It reports position at a moment.
Structure, also fixed:
- Non-current assets: fixed assets at carrying value, financial assets.
- Current assets: inventories, trade and other receivables, cash and cash equivalents.
- Equity: ordinary share capital and retained income.
- Non-current liabilities: loans repayable after twelve months.
- Current liabilities: trade and other payables, short-term loan portion, bank overdraft.
The classification that costs marks most often is the loan. The portion repayable within the next twelve months is a current liability, and the rest is non-current. A loan sitting entirely in non-current when the question told you the annual repayment is a lost mark, and the question always tells you.
Carrying value is cost minus accumulated depreciation. Write both and then the difference, because the memo pays for the working.
Three: the Cash Flow Statement
The one students dread, and the one with the most rigid structure, which makes it learnable.
Three sections, always in this order: operating activities, investing activities, financing activities.
The idea that unlocks it: profit is not cash. The cash flow statement exists to reconcile the two. So you start with profit before tax and undo everything in the profit figure that did not involve cash moving.
- Add back depreciation, because it reduced profit without any cash leaving.
- Adjust for changes in working capital: an increase in inventory or receivables used cash, an increase in payables provided it.
- Then subtract the tax and interest actually paid, which may differ from what was charged.
For investing, fixed assets purchased is a cash outflow and proceeds on disposal an inflow. For financing, shares issued and loans raised are inflows, and dividends paid and loans repaid are outflows.
The check at the end is not optional. The net change across all three sections must equal the actual movement in cash and cash equivalents between the two balance sheet dates. If it does not, something is wrong and you have a chance to find it.
Four: ratio analysis and interpretation
Calculating the ratio is half the marks. Interpreting it is the other half, and it is the half left behind.
The ones examined most:
$$\text{Current ratio} = \frac{\text{current assets}}{\text{current liabilities}}$$
$$\text{Acid test ratio} = \frac{\text{current assets} - \text{inventory}}{\text{current liabilities}}$$
$$\text{Debt equity ratio} = \frac{\text{non-current liabilities}}{\text{owners equity}}$$
$$\text{Return on equity} = \frac{\text{net profit after tax}}{\text{average owners equity}} \times 100$$
An interpretation answer needs three things, and the third is the one people miss:
- Quote the actual figure, both years.
- Say whether it improved or worsened.
- Say what that means for the business, in a sentence about the business rather than about the number.
So not "the current ratio decreased from 2.1:1 to 1.4:1". That is only part one and two. The full answer adds that the business is less able to pay its short-term debts from short-term assets, though 1.4:1 is still within the generally acceptable range of 1.5:1 to 2:1, so it is a decline rather than a crisis.
The question that asks whether a shareholder should be satisfied is asking you to compare return on equity against the interest rate on alternative investments. If the return on equity exceeds what the money would earn in the bank, the shareholder is better off in the business. Say the comparison out loud in your answer.
Five: inventory systems and valuation
Two systems. Perpetual updates the trading stock account on every transaction. Periodic works it out at the end by physical count.
Two valuation methods examined: FIFO, first in first out, and weighted average. Know how to compute both, and know the consequence: when prices are rising, FIFO leaves the newer, more expensive stock on hand, so closing stock is valued higher and reported profit is higher. Weighted average smooths it.
The trading stock deficit is the difference between what the records say should be there and what the count found. It is an expense.
Six: internal control and ethics
Worth real marks, answered vaguely, and entirely preparable.
When asked what internal control measure should be put in place, answer with a specific, checkable action, not a principle. Not "they should be more careful with cash". Rather: two people should count the cash and both sign the record, deposits should be made daily, and the person who records receipts should not be the person who banks them.
That last idea is division of duties, and it is the single most useful concept in this section. The person who authorises a transaction, the person who records it, and the person who holds the asset should be three different people. Most control answers are an application of it.
For the ethics questions, name the specific breach and say who was harmed. A director using company funds for private expenses has breached their fiduciary duty to act in the best interests of the company, and the harm falls on the shareholders whose funds those are.
How to prepare
Accounting rewards doing whole questions under time pressure more than any other NSC subject, because the format is muscle memory and muscle memory does not come from reading.
Work full past paper questions with a timer, then mark against the official memo line by line. What you will find is that a large share of your lost marks are format marks: a missing heading, an omitted subtotal, a figure in the wrong column. Those are fixable in a week and they are worth more than another week of theory.
Braintiq works from your own documents. Upload your past papers, memos and class notes into a subject space, and what it builds comes from those pages.
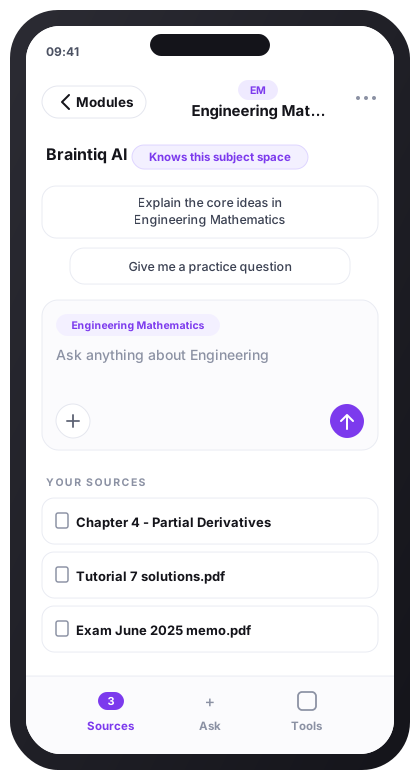
Each section of a generated study pack reports how many of its claims could be traced back to a page in your own documents, and anything that could not be traced is marked rather than hidden. For a subject with a prescribed format that matters, because a plausible-looking layout that is not the required one is hard to catch by eye.
You can use it without an account at braintiq.app/try.
The short version
- Assets equal owners equity plus liabilities. Every transaction keeps it balanced.
- The four named subtotals in the income statement are each a mark. Label them.
- The portion of a loan repayable within twelve months is a current liability.
- Profit is not cash. The cash flow statement reconciles the two, starting with depreciation added back.
- An interpretation needs the figure, the direction, and what it means for the business.
- Under rising prices FIFO reports higher closing stock and higher profit.
- Internal control answers must be specific actions, and most of them are division of duties.
- Most lost marks in this subject are format marks, and format is the cheapest thing to fix.